
Fixed indexed annuities (FIAs) are insurance contracts that link returns to a market index while providing a guaranteed minimum floor. For Denver retirees, these products can offer a way to generate income without direct market exposure. However, understanding the specific mechanics of caps, participation rates, and surrender charges is critical before committing funds. Reynolds Insurance Solutions helps Colorado residents navigate these complex contracts with clarity and confidence. For additional details, review the .
How Fixed Indexed Annuities Function
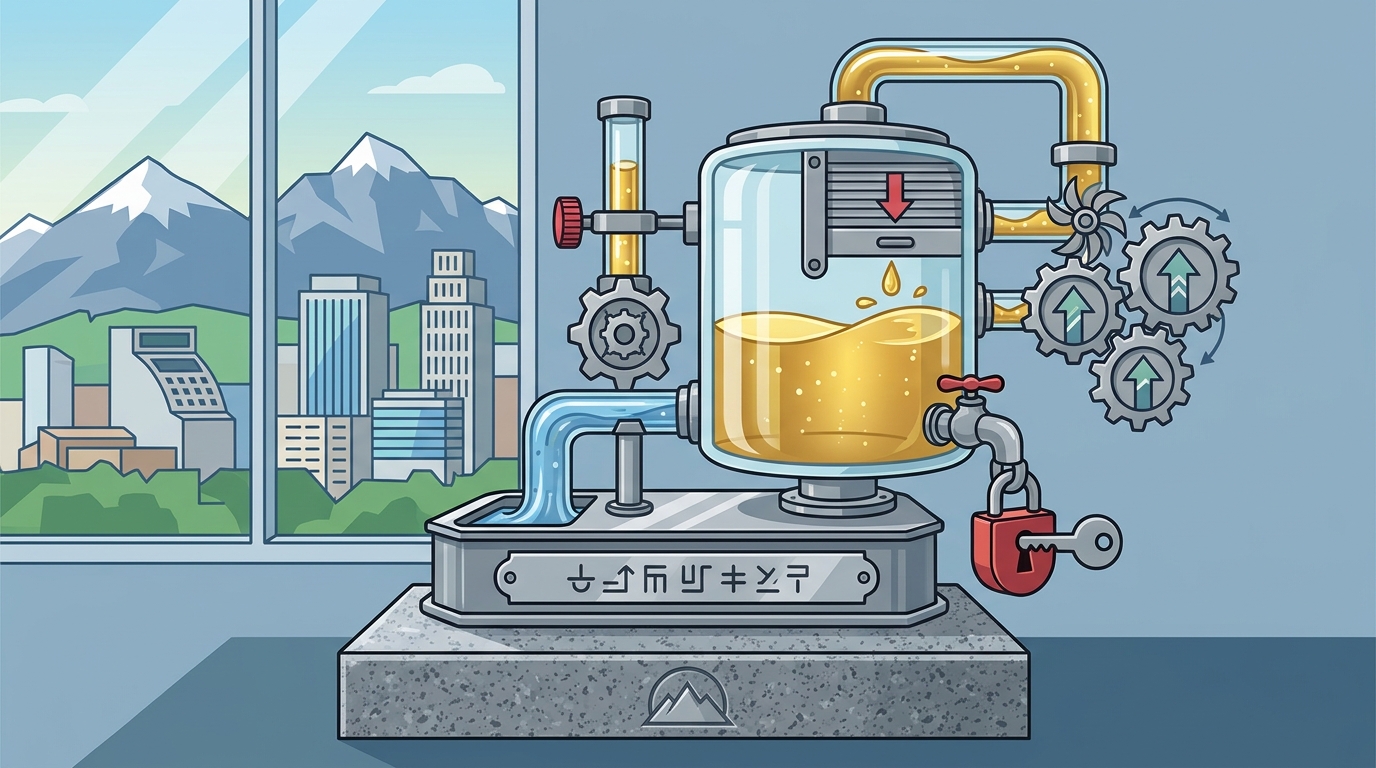
A fixed indexed annuity is a type of annuity that credits interest based on the performance of a selected stock market index, such as the S&P 500. Unlike direct investments, the principal is protected from market losses, meaning the value cannot drop below the guaranteed minimum. This structure appeals to retirees who want growth potential without the volatility of direct equity holdings. The contract specifies a crediting method, which determines how index gains are translated into account value. For additional details, review the Customer Experience.
The most common crediting methods include caps, participation rates, and multipliers. A cap limits the maximum interest rate credited in a given period, regardless of how high the index rises. A participation rate determines the percentage of the index gain that is credited to the account. For example, if an index rises by 10% and the contract has a 50% participation rate, only 5% is credited. Understanding these variables is essential for evaluating the true earning potential of the product. For additional details, review the Frequently Asked Questions.
Balancing Income and Growth Potential
Retirees often seek a balance between preserving capital and generating reliable income. FIAs can serve as a component of a diversified retirement portfolio, providing a stable base while other assets handle growth. The income phase of an FIA typically begins after an accumulation period, during which the account value grows based on index performance. Once the income phase starts, the contract may offer a lifetime income stream, often with a guaranteed minimum payout. For additional details, review the About.
It is important to note that the income amount is calculated based on the account value at the time of conversion. Higher index gains during the accumulation phase can lead to higher income payments. However, the guaranteed minimum income is usually lower than the potential income based on market performance. Retirees should carefully review the income calculation formula and any associated rider costs before selecting an FIA.
Understanding Costs and Liquidity Restrictions
Fixed indexed annuities are not free, and they come with various costs and restrictions that can impact overall returns. Surrender charges are fees applied if the contract is surrendered before a specified period, typically ranging from 7 to 10 years. These charges decrease over time, allowing for partial withdrawals without penalty after a certain period. Withdrawal restrictions limit the amount that can be taken out each year, often around 10% of the account value, without incurring surrender charges.
Additionally, riders for enhanced income or long-term care benefits may carry annual fees, which can reduce the account value. These fees are typically deducted from the account balance, effectively lowering the interest credited. Retirees should request a detailed breakdown of all fees and charges, including any market value adjustments (MVAs) that may apply if the contract is surrendered early. MVAs can significantly reduce the payout value if market conditions are unfavorable.
Tax Implications for Colorado Residents
Tax treatment is a significant consideration for retirees in Colorado. Earnings within an FIA grow on a tax-deferred basis, meaning taxes are not paid on interest or index gains until withdrawals are made. This can be advantageous for retirees who are in a lower tax bracket during retirement. However, ordinary income tax is applied to the earnings portion of withdrawals, while the principal is returned tax-free. It is important to consult with a tax professional to understand the specific implications for your situation.
Colorado does not have a state capital gains tax, but it does tax ordinary income. Therefore, the tax-deferred growth of an FIA can be beneficial, but retirees should be aware of the potential tax liability when taking distributions. Additionally, the Required Minimum Distribution (RMD) rules apply to certain annuity contracts, requiring withdrawals to begin by a specific age. Understanding these rules is crucial for avoiding unnecessary tax penalties.
Why Choose Reynolds Insurance Solutions
Reynolds Insurance Solutions provides straightforward guidance on fixed indexed annuities for individuals, families, pre-retirees, retirees, and business owners in Colorado. Our team helps clients understand the complexities of FIA contracts, including caps, participation rates, and surrender charges. We focus on aligning annuity solutions with your specific retirement goals and financial circumstances. By working with an independent producer, you gain access to multiple carriers and can compare options to find the best fit for your needs.
Our approach is centered on education and transparency. We ensure that you understand all aspects of the contract, including potential risks and limitations. Whether you are looking to supplement Social Security income or create a reliable retirement stream, Reynolds Insurance Solutions is here to help you make informed decisions. We are committed to providing the support and expertise you need to protect what matters most.
Key Takeaways
- Fixed indexed annuities link returns to a market index while protecting principal from market losses.
- Caps and participation rates limit the maximum interest credited, so it is important to understand these variables.
- Surrender charges and withdrawal restrictions can limit liquidity, so plan for long-term commitment.
- Riders for enhanced income or long-term care benefits may carry annual fees that reduce account value.
- Earnings grow on a tax-deferred basis, but ordinary income tax applies to withdrawals.
- Reynolds Insurance Solutions offers independent guidance to help Colorado retirees navigate FIA options.
Frequently Asked Questions
What is a fixed indexed annuity?
A fixed indexed annuity is an insurance contract that credits interest based on the performance of a market index while providing a guaranteed minimum floor.
How do caps and participation rates work?
Caps limit the maximum interest rate credited, while participation rates determine the percentage of index gains credited to the account.
Are fixed indexed annuities FDIC-insured?
No, fixed indexed annuities are insurance products and are not FDIC-insured or SIPC-protected. They are backed by the claims-paying ability of the issuing insurance company.
What are surrender charges?
Surrender charges are fees applied if the contract is surrendered before a specified period, typically ranging from 7 to 10 years.
How are fixed indexed annuities taxed?
Earnings within an FIA grow on a tax-deferred basis, but ordinary income tax is applied to the earnings portion of withdrawals.
Can I withdraw money from a fixed indexed annuity?
Yes, but withdrawal restrictions limit the amount that can be taken out each year, often around 10% of the account value, without incurring surrender charges.
Conclusion
Fixed indexed annuities can be a valuable tool for Denver retirees seeking to balance growth and stability in their retirement portfolios. By understanding the mechanics of caps, participation rates, and surrender charges, you can make informed decisions that align with your financial goals. Reynolds Insurance Solutions is dedicated to providing clear and comprehensive guidance on these products, ensuring that you have the knowledge and support you need to protect your future. To explore how fixed indexed annuities can fit into your retirement plan, contact Reynolds Insurance Solutions today.