
Long-term care rider options vary significantly by state due to distinct regulatory frameworks and carrier availability. In Colorado, where Reynolds Insurance Solutions operates, residents can access riders attached to life insurance or annuity contracts. These riders provide benefits for chronic illness or long-term care needs. Understanding your state's specific rules is critical for selecting the right coverage.
Defining the Core Coverage
Long-term care insurance is coverage that lasts at least 12 months in a row if you have a serious illness or disability that lasts a long time, according to the Office of the Insurance Commissioner. A long-term care rider is an optional add-on to a life insurance or annuity policy that converts a portion of the death benefit or principal into care benefits. Chronic illness is a condition that requires assistance with at least two activities of daily living (ADLs) for 90 days or more. For additional details, review the .
These definitions matter because state regulators define eligibility differently. Some states require a physician's certification of cognitive impairment, while others focus strictly on physical ADLs. In Colorado, the Colorado Division of Insurance oversees these products. The specific definition of "chronic illness" in your policy must align with state law to ensure benefits are payable. For additional details, review the Customer Experience.
Regulatory Differences Across States
Washington State offers a notable contrast with its innovative universal social long-term care insurance program, as noted in PubMed research. This public program coexists with private riders, creating a complex landscape for residents. In Colorado, private riders remain the primary mechanism for individuals seeking supplemental care coverage. You must verify which carriers operate in your specific state before comparing rider features.
Common Rider Structures
Most riders fall into two categories: life insurance riders and annuity riders. Life insurance riders, such as CareChoice One and CareChoice Select, are whole life policies with long-term care riders, according to CompareLongTermCare.org. These policies allow you to use the death benefit for care if needed, or leave it to heirs if you do not.
Annuity riders combine income and care protection in one plan, giving you flexibility if health needs change later in life, as explained by Annuity.org. This structure is particularly relevant for retirees seeking guaranteed income. The key difference is the trigger: life insurance riders often require a higher level of disability, while annuity riders may activate based on chronic illness. At Reynolds Insurance Solutions, we help clients evaluate which structure aligns with their estate goals and care needs.
Cost and Benefit Implications
It is crucial to understand that using rider benefits reduces the remaining death benefit or annuity principal. This is not a free benefit. The reduction is governed by the specific policy terms. In Colorado, consumers should review the "benefit reduction schedule" in the policy contract. This schedule outlines exactly how much of the death benefit is consumed per day or month of care. Transparency in this schedule is a key factor in choosing a carrier.
Colorado Availability and Carrier Options
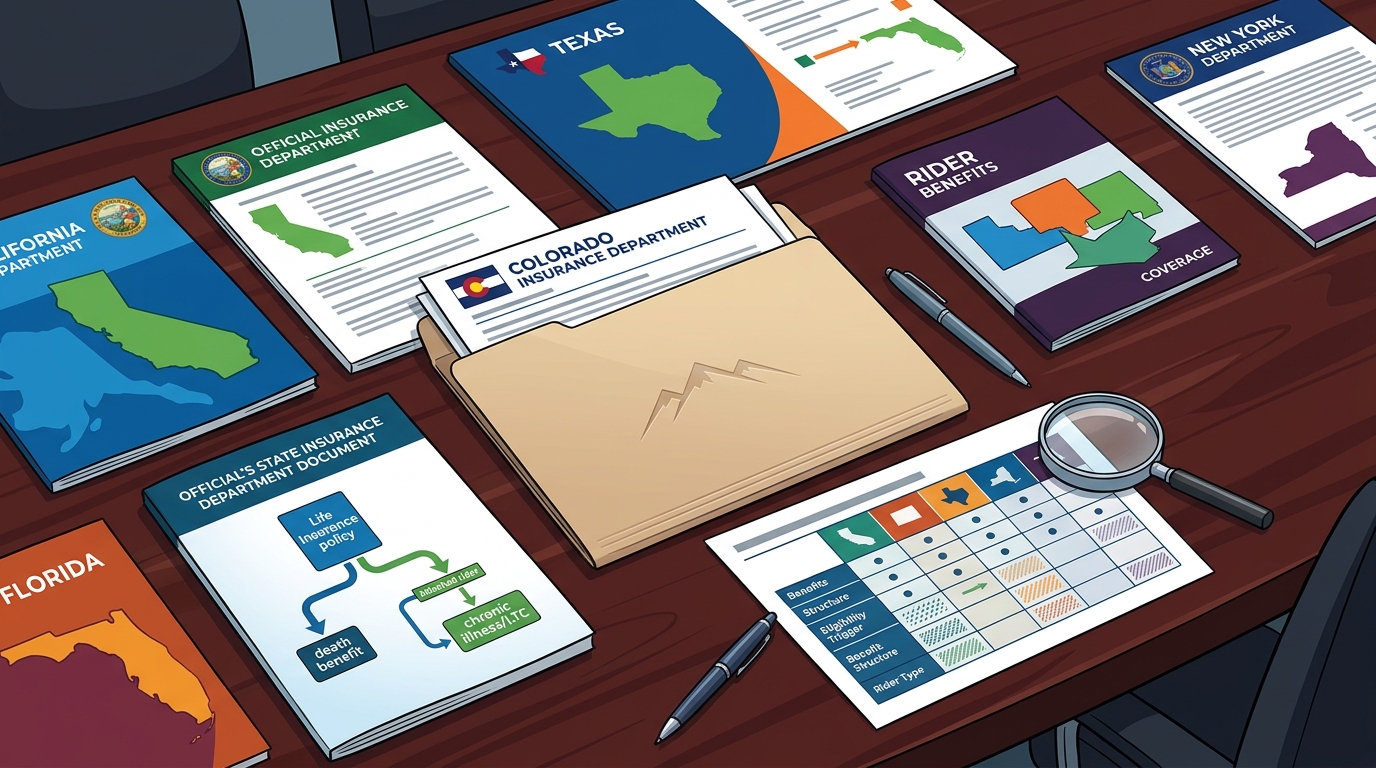
Carrier availability is the most practical constraint for Colorado residents. Not every national carrier sells riders in every state. Genworth, for example, reported that it began selling individual long-term care through CareScout Insurance Company in October 2025 and ceased sales through Genworth Life Insurance Company, according to CompareLongTermCare.org. This shift impacts which products are accessible to Colorado buyers.
Key Takeaways
- Life insurance riders convert death benefits into care funds, while annuity riders convert principal into care income.
- Using rider benefits reduces the remaining policy value or death benefit.
- Washington State's universal program highlights the contrast between public and private care coverage.
- Independent producers like Reynolds Insurance Solutions can compare multiple carriers to find the best fit.
Frequently Asked Questions
Do long-term care riders work in all states?
No, rider availability depends on state regulations and carrier licensing. Some states have specific requirements for rider definitions and benefit structures that limit which products can be sold.
How does a rider affect my death benefit?
Using long-term care benefits from a rider reduces the remaining death benefit. The specific reduction amount is outlined in the policy's benefit reduction schedule.
Can I add a rider to an existing policy?
In most cases, riders must be added at the time of policy issuance. Adding a rider to an existing policy is rare and subject to underwriting and carrier approval.
What is the difference between a chronic illness rider and a long-term care rider?
Chronic illness riders typically activate when you need help with two or more activities of daily living. Long-term care riders may have stricter definitions, often requiring a higher level of disability or cognitive impairment.
Are riders more expensive than standalone long-term care insurance?
Rider premiums are generally lower than standalone long-term care insurance premiums for the same benefit amount. However, the total cost of the base policy plus the rider should be compared to standalone options.
Does Reynolds Insurance Solutions sell riders in Colorado?
Yes, Reynolds Insurance Solutions offers life insurance and annuity products with riders in Colorado, subject to carrier availability and individual underwriting.
Next Steps for Colorado Residents
Selecting the right long-term care rider requires a detailed review of your state's regulations and your personal financial goals. The regulatory landscape is complex, and carrier availability in Colorado is specific. By understanding the definitions, costs, and implications of each rider type, you can make an informed decision. Reynolds Insurance Solutions provides straightforward guidance to help you navigate these options. To plan your visit, for a personalized review of your coverage needs.